Where crypto payments still feel painful today
Crypto payments still feel harder than they should because the “simple” act of paying hides a stack of decisions the user didn’t ask to make. They’re forced to pick a chain, choose a token, estimate network fees, and interpret wallet prompts that read like system logs. A checkout that takes two seconds with cards can turn into a multi-minute detour: switching networks, topping up gas, waiting on confirmations, then wondering whether the merchant actually received it.
Merchants feel the pain differently. They face volatile settlement value, reconciliation across wallets and chains, chargeback-like disputes without card-style tooling, and compliance questions that show up late in the flow. Even when the tech works, support costs climb because every failed payment looks unique: wrong network, insufficient gas, stale quotes, phishing popups, or wallet UX differences. The result is a product problem, not a protocol problem.
What “AI improvement” actually means in this space
Watch what happens when a user pings support with “my payment is stuck.” Most teams treat that as a ticketing problem, but it’s really an interpretation problem: you need to map messy inputs (wallet type, chain state, token approvals, mempool conditions, merchant expectations) into a concrete next step. “AI improvement” in crypto payments usually means reducing the number of moments where humans must translate ambiguity into action.
That doesn’t require a chatbot bolted onto checkout. The highest-value uses look like prediction and classification wrapped around existing workflows: flagging likely-to-fail payments before the user signs, choosing the right rails given constraints, and turning on-chain events into plain-language statuses for users and ops. If the model guesses wrong, you don’t just lose a conversion; you can misroute funds, trigger compliance work, or create liabilities you can’t reverse.
Smarter routing and fees at the moment of payment
A familiar failure mode is a checkout that “works” in the happy path but collapses when conditions shift: gas spikes between quote and signature, a route relies on thin liquidity, or the user’s wallet can’t simulate the call cleanly. Smarter routing is less about finding the mathematically cheapest path and more about choosing the path most likely to settle quickly and predictably for this user, right now. That can mean preferring a slightly higher fee on a more reliable chain, switching from an on-chain swap to a pre-funded merchant route, or bundling steps (approval plus transfer) when the wallet supports it.
AI helps when it turns live signals into a single recommended option: expected confirmation time, probability of revert, total fees across hop(s), and slippage risk based on recent pool behavior and the user’s balance/allowance state. If the model “optimizes” into a route that fails, you own the support load and possibly the make-good. Treat routing outputs like risk-scored suggestions with guardrails, not autonomous decisions.
Fraud, compliance, and trust signals without killing UX
A checkout that feels “trustless” to engineers can still feel suspicious to users. The user sees an unfamiliar token contract, a spender approval for “unlimited,” or a last-second network switch, and their safest move is to abandon. Merchants have a different fear: the payment clears on-chain but later gets tied to sanctions exposure, stolen funds, or structured activity that triggers an investigation after you’ve already delivered value.
AI is useful here when it collapses noisy risk inputs into simple, explainable cues at the right moment: “This address is new and has no history,” “This route requires an unlimited approval,” “Funds originated from a known mixer cluster,” or “This pattern matches prior refund abuse.” The goal is not to add more warnings, but to replace generic popups with ranked, contextual friction: allow, step-up (extra confirmation, smaller limits, delayed fulfillment), or block.
False positives kill conversion and damage trust; false negatives create regulatory and loss exposure. Treat models as triage, log every decision, and keep a deterministic fallback policy when the signals are missing or uncertain.
AI wallets and agents: convenience versus control
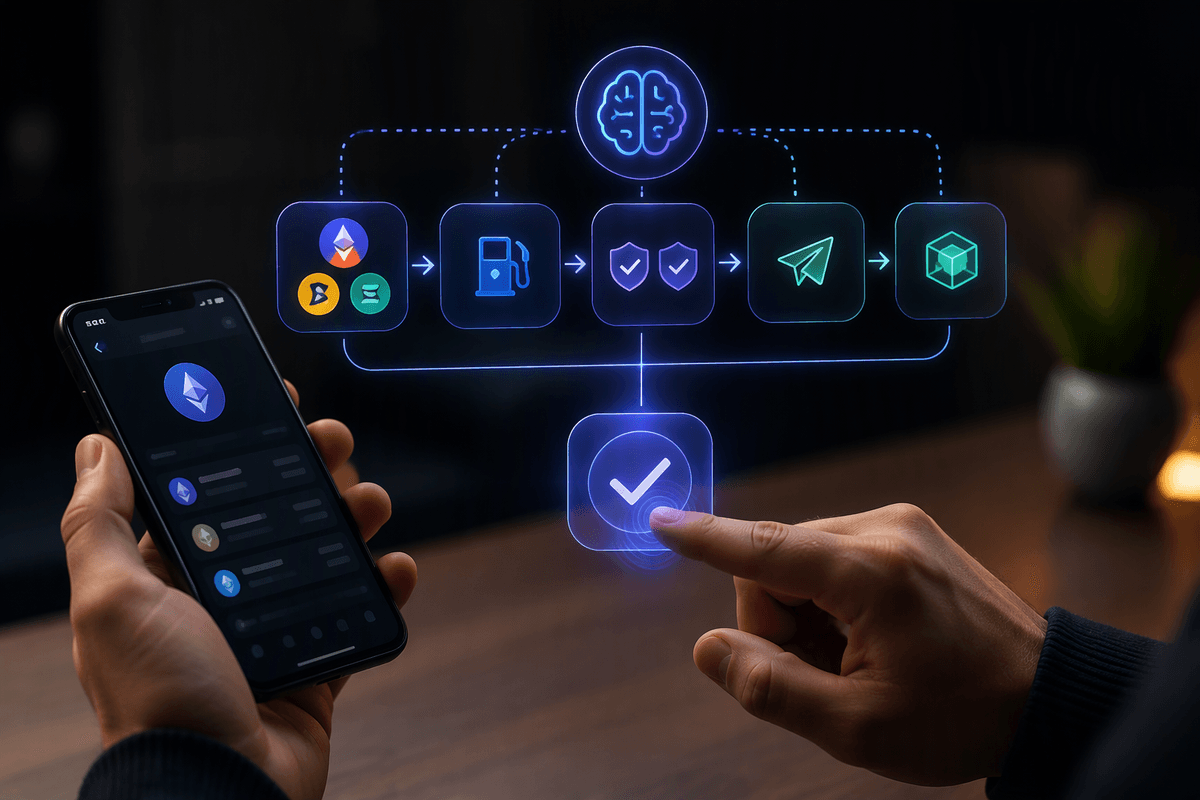
Users don’t really want “an AI wallet.” They want the wallet to behave like a competent operator: know what they’re trying to do, line up the prerequisites, and avoid surprises. That’s where agents start to look attractive in payments flows—auto-choosing a token to spend, topping up gas, batching approvals with the transfer, or retrying with a safer route when simulation looks shaky. Done well, the experience shifts from “sign three times and hope” to “confirm intent once and track progress,” which is a real conversion lever.
An agent that can move funds, set approvals, or rotate between chains expands your blast radius from “user clicked the wrong button” to “the system acted on a bad assumption.” Hallucinations aren’t the main risk; silent misinterpretation is. The hard requirement is policy: explicit spending limits, allowlists for contracts and destinations, time-bound permissions, and a clear “why” for each action. Otherwise convenience becomes an un-auditable delegation layer that ops and regulators will still hold you accountable for.
Web3 apps that adapt: support, onboarding, and discovery
Most Web3 apps still treat every user like a power user: they land on a blank dashboard, connect a wallet, and are expected to already know which chain, token, and action sequence makes sense. In practice, the first real product moment is confusion—“why did this fail,” “what am I signing,” “where did my funds go”—and teams pay for it in support tickets and churn. An adaptive layer can turn raw context (wallet type, balances, recent on-chain activity, geo constraints, prior retries) into a guided path: the single safest network, the right funding step, a human-readable explanation of the signature, and a status page that updates from chain events without forcing the user to interpret hashes.
Discovery benefits too: suggest features based on observed intent (swap, pay, bridge, stake) instead of menus, and route users into the smallest viable flow. If you over-personalize from a thin on-chain history or misclassify intent, you create bad defaults that look like dark patterns. Guardrails matter: show alternatives, keep reversibility where possible, and make “talk to a human” easy when the model is uncertain.
The hard parts: data quality, privacy, and liability
The quickest way to get “smart” behavior that still fails users is to feed models the wrong reality. On-chain data is public, but messy: address clusters are probabilistic, labels go stale, and the same user can look like ten different entities across wallets and chains. Off-chain data is worse: support tickets, device signals, KYC outcomes, and chargeback-style disputes live in separate systems with inconsistent identifiers. If you can’t reliably join events into a single timeline, your risk scores and routing predictions will look confident and be wrong in precisely the edge cases that create losses.
Privacy and liability show up as product constraints, not legal footnotes. Sending wallet addresses, transaction metadata, or user prompts to third-party model providers can conflict with internal policies, regional rules, or customer expectations, even if the data is “public.” Meanwhile, a model-driven “allow” decision is still your decision when regulators, partners, or users ask why it happened. Plan for storage limits, audit logs, deterministic fallbacks, and a clear policy owner—or expect AI to raise support costs and compliance exposure instead of lowering them.
How to start: pick one workflow and measure it
A recognizable starting point is the support queue: “payment stuck,” “wrong network,” “failed swap,” “funds not received.” Pick one high-volume workflow and define success in operational terms: fewer tickets per 1,000 checkouts, faster time-to-resolution, higher completion rate after a failure, lower manual review minutes per case. Instrument the baseline first, including where users abandon and which errors repeat.
Then add a narrow AI component that only recommends actions, not executes them: classify the failure reason, generate a plain-language status, suggest the safest next step, and route edge cases to humans. Keep a deterministic fallback and sample audits, because the first hidden cost will be mislabels that feel “helpful” but send users in circles.